Personal Loan Tips for Diwali 2026: The festive season often brings additional expenses for families across India. From shopping and home renovation to travel, celebrations and household purchases, spending can increase significantly during Diwali and Chhath Puja.
To manage these expenses, some people consider taking a personal loan from a bank or non-banking financial company (NBFC).
Financial institutions may also introduce special offers during the festive season, including promotional interest rates, processing fee discounts and faster loan approvals.
However, choosing a personal loan simply because it offers a low advertised interest rate can be an expensive mistake.
The actual cost of borrowing depends on several factors, including processing fees, repayment tenure, credit score, monthly EMI and prepayment conditions.
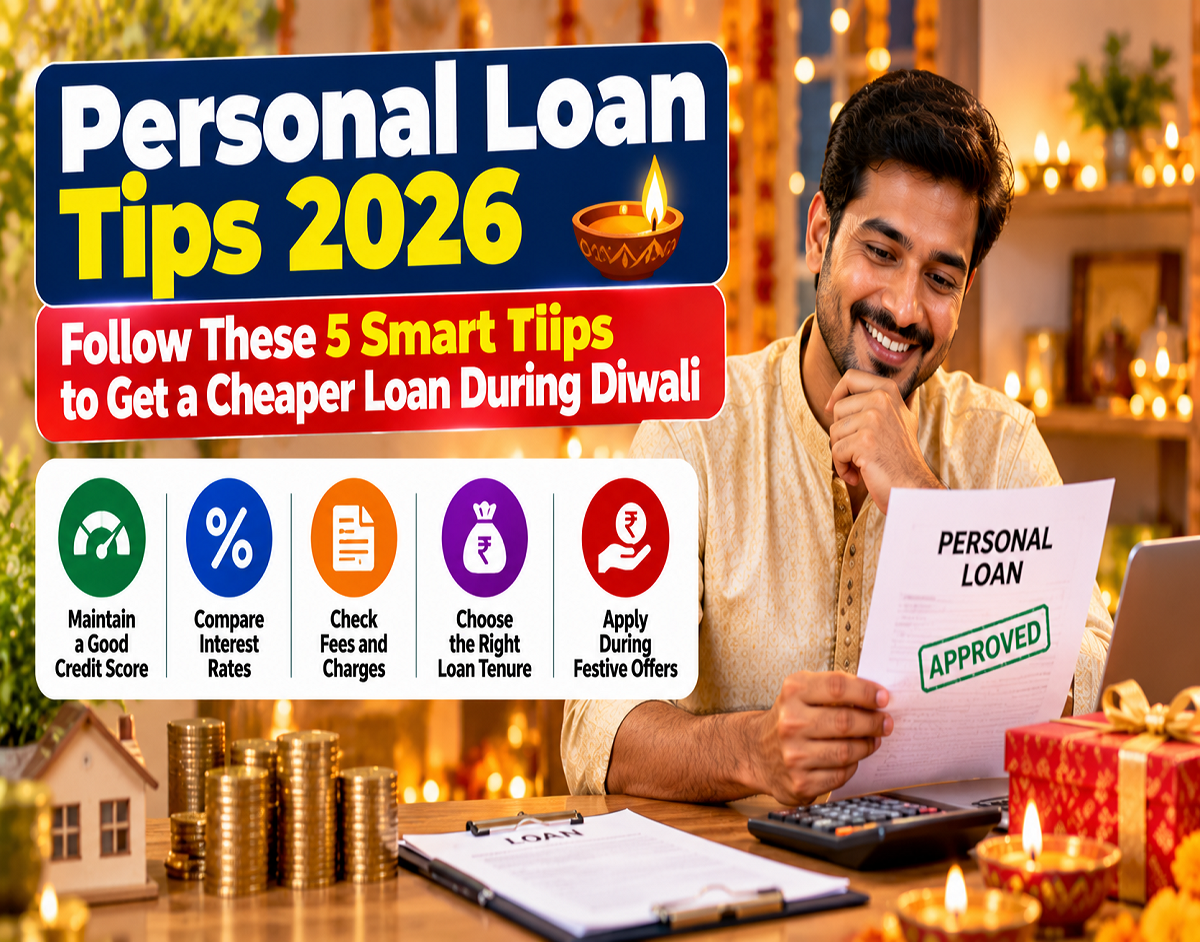
Here are five important tips that can help borrowers compare personal loans and avoid unnecessary expenses.
1. Compare the Total Loan Cost, Not Just the Interest Rate
The first step in choosing a personal loan is comparing offers from different lenders.
Banks may offer different interest rates to customers depending on their income, employment history, credit profile and existing financial obligations.
Even two applicants borrowing the same amount may receive different interest rate offers.
Therefore, borrowers should compare the available options rather than accepting the first offer.
However, the interest rate alone does not reveal the full borrowing cost.
A lender offering a slightly lower interest rate may charge higher processing fees or other upfront costs.
To understand the overall expense, borrowers should review the Annual Percentage Rate (APR).
APR represents the annualised cost of credit, taking into account the interest rate and applicable charges included under the relevant disclosure rules.
Under RBI requirements, regulated lenders provide a Key Facts Statement (KFS) containing important loan information, including the APR.
Borrowers should carefully review this document before accepting a loan offer.
2. Check Processing Fees and Hidden Charges
Most banks and financial institutions charge a processing fee for personal loans.
The fee may be calculated as a percentage of the sanctioned amount or charged as a fixed amount.
Other applicable expenses may include taxes on fees, late payment penalties and certain service charges.
Consider an example involving a ₹2 lakh personal loan.
| Particulars | Bank A | Bank B |
|---|---|---|
| Loan amount | ₹2,00,000 | ₹2,00,000 |
| Processing fee | 1% | 2% |
| Processing fee amount | ₹2,000 | ₹4,000 |
| Difference | — | ₹2,000 more |
In this example, Bank B charges ₹2,000 more in processing fees than Bank A.
If the fee is deducted before disbursement, the amount credited to the borrower's account may be lower than the sanctioned loan amount.
Applicable taxes can further increase the upfront expense.
However, the lender with the lower processing fee is not automatically the cheaper option.
Borrowers should compare the total repayment amount, APR and all applicable charges before making a decision.
3. Choose an EMI That Fits Your Monthly Budget
The Equated Monthly Instalment (EMI) is one of the most important factors when taking a personal loan.
Borrowers should select a repayment amount that fits comfortably within their monthly income and regular household expenses.
A longer loan tenure can reduce the EMI, but it generally increases the total interest paid.
For example, consider a ₹1 lakh personal loan at an annual interest rate of 12%.
₹1 lakh loan at 12% annual interest
3-year tenure
₹3,321
Approx. monthly EMI
5-year tenure
₹2,224
Approx. monthly EMI
The five-year option reduces the monthly EMI by approximately ₹1,097.
However, the borrower continues paying interest for two additional years.
This increases the overall interest expense.
Therefore, borrowers should choose a repayment period that balances affordability with the total cost of the loan.
4. Check Your Credit Score Before Applying
A borrower's credit score can influence personal loan approval and the interest rate offered by a lender.
A strong credit history may improve the chances of receiving more competitive terms.
However, loan approval also depends on other factors, including income stability, existing debt and lender-specific eligibility requirements.
Before applying for a personal loan, borrowers should review their credit report.
If there are incorrect entries, they should raise a dispute with the relevant credit information company or lender.
Timely repayment of existing loans and credit card bills can help maintain a healthy credit profile.
Borrowers should also avoid submitting numerous loan applications without comparing eligibility requirements.
Multiple hard credit enquiries within a short period may affect the credit profile considered by lenders.
Checking available offers carefully before submitting formal applications can help reduce unnecessary enquiries.
5. Understand Prepayment and Foreclosure Rules
Personal loans are often repaid over several years.
However, borrowers may sometimes receive a bonus, additional income or savings that allow them to repay the loan earlier.
Early repayment can reduce future interest expenses.
But borrowers should first check whether the lender charges a prepayment or foreclosure fee.
Some loan products permit partial prepayments, while others have specific restrictions.
The rules may depend on the loan's interest rate structure, sanction date, borrower category and applicable RBI regulations.
Borrowers should not assume that every personal loan attracts a foreclosure penalty.
They should obtain written information about the applicable charges and restrictions before signing the agreement.
Personal Loan EMI Calculator: Compare 10%, 12% and 14% Interest Rates
A small difference in the annual interest rate can significantly affect the overall borrowing cost.
Consider a personal loan of ₹1 lakh with a repayment period of three years.
Loan amount: ₹1,00,000 | Tenure: 36 months
| Interest rate | Monthly EMI | Total interest |
| 10% | ₹3,227 | ₹16,170 |
| 12% | ₹3,321 | ₹19,571 |
| 14% | ₹3,418 | ₹23,037 |
Approximate figures from the supplied report. Processing fees, taxes and other charges are excluded.
At a 10% interest rate, the total interest is approximately ₹16,170.
At 14%, the interest expense increases to approximately ₹23,037.
This represents a difference of around ₹6,867 over the three-year repayment period.
The example shows why comparing interest rates is important when the loan amount and tenure are identical.
Try This Personal Loan EMI Calculator
You can also estimate your EMI by changing the loan amount, annual interest rate and repayment tenure.
Loan amount
₹2,00,000
Annual interest rate
12.0%
Repayment tenure
3 years
Estimated monthly EMI
₹6,643
Total interest
₹39,143
Total repayment
₹2,39,143
Illustrative reducing-balance EMI calculation. Excludes processing fees, taxes and other charges.
Should You Take a Personal Loan for Diwali Shopping?
A personal loan can help cover an immediate expense, but it also creates a repayment obligation.
Before borrowing for festive purchases, customers should consider whether the expense is necessary and whether it can be managed through existing savings.
Borrowing for discretionary purchases may not be suitable if it creates pressure on essential household spending.
It is also important to maintain sufficient funds for regular expenses and unexpected emergencies.
A promotional loan offer should be evaluated on its actual financial terms rather than the urgency created by a festive-season advertisement.
Personal Loan Tips 2026: Final Takeaway
Taking a personal loan during Diwali or Chhath Puja requires careful planning.
A lower interest rate can reduce borrowing costs, but it is equally important to check processing fees, EMI affordability, credit score requirements and prepayment conditions.
Comparing the Key Facts Statement and APR across lenders can help borrowers understand the true cost of borrowing.
The most important rule is to choose a loan based on the total repayment amount and your ability to repay comfortably, rather than simply selecting the lowest advertised EMI.
Disclaimer: This article is for general financial awareness. Loan eligibility, interest rates, fees and repayment conditions vary by lender. EMI calculations are illustrative and do not constitute a loan offer or personalised financial advice.