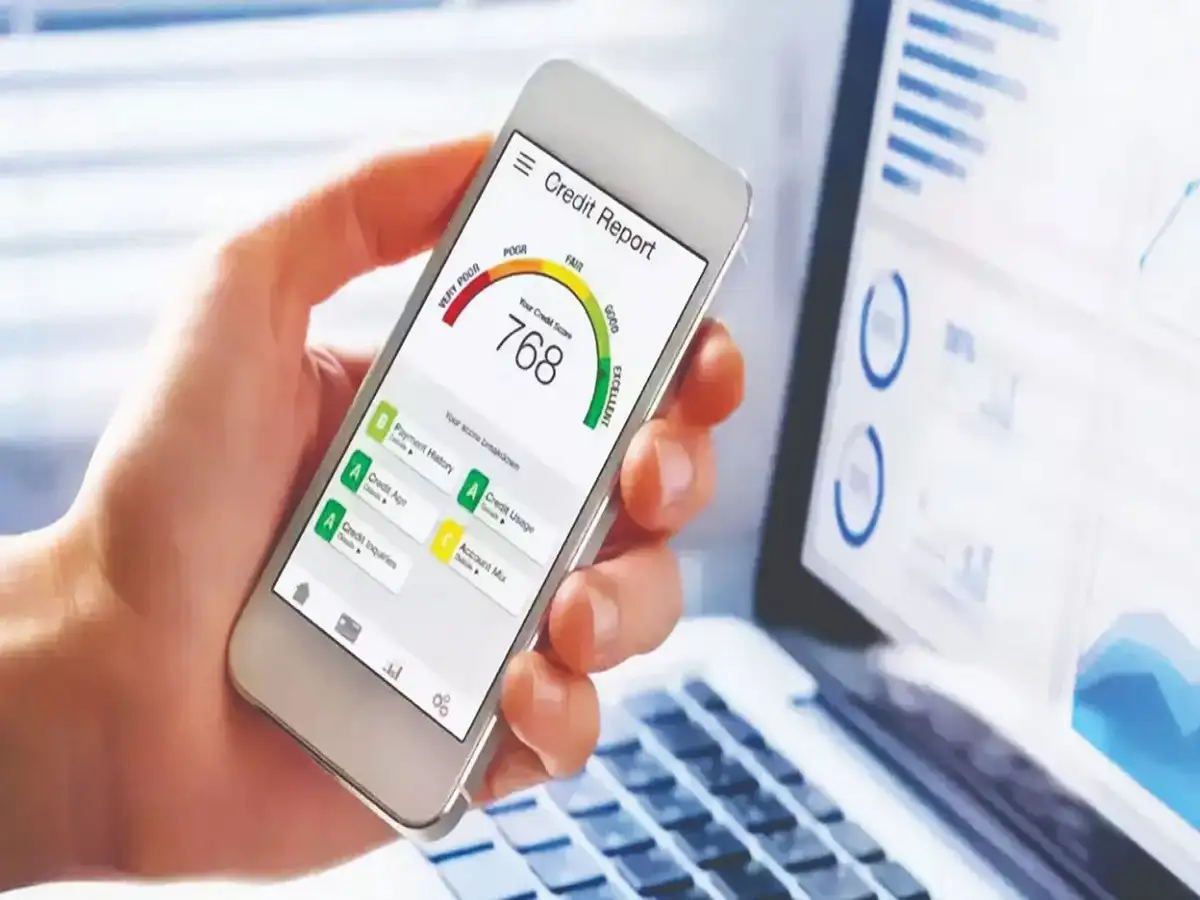
A healthy credit profile can make an important difference when you apply for a home loan, car loan, personal loan or credit card. One of the commonly used indicators of an individual's credit behaviour in India is the CIBIL Score, a three-digit number ranging from 300 to 900.
The score reflects information contained in your credit history, including borrowing and repayment behaviour. Lenders can consider a credit score along with several other factors when deciding whether to approve a loan or credit card application.
Building or improving a credit score usually takes time. At the same time, repeated financial mistakes—such as paying EMIs late, maintaining very high credit utilisation or frequently applying for new credit—can negatively affect your overall credit profile.
If your credit score has fallen, avoiding the following mistakes can help you work towards healthier credit behaviour.
1. Don't Repeatedly Delay EMIs or Credit Card Payments
Payment history is an important part of a borrower's credit profile. Missing an EMI or repeatedly paying a credit card bill after its due date can be reflected in your credit history when reported by the lender.
Late payments can create more than one financial problem. Apart from their potential impact on your credit profile, delayed payments may result in late fees, interest charges or other penalties, depending on the lender's terms.
The simplest approach is to build a repayment routine that reduces the possibility of accidentally missing a due date.
You can set payment reminders or enable auto-pay or auto-debit facilities where appropriate. If automatic payments are enabled, ensure that the linked bank account has sufficient funds before the due date.
Credit card users should also understand the difference between paying the minimum amount due and clearing the entire outstanding balance. Paying only the minimum amount may keep the account from being treated the same way as a completely missed payment, but the remaining balance can continue attracting applicable interest and charges. Clearing the full amount due, whenever financially possible, can help avoid revolving high-cost credit.
2. Avoid Consistently Using Almost Your Entire Credit Limit
Another factor worth monitoring is your credit utilisation ratio, which broadly indicates how much of your available revolving credit you are using.
Suppose your credit card has a limit of Rs 1 lakh and your outstanding balance regularly approaches that entire amount. Such consistently high utilisation can indicate heavy dependence on available credit.
Maintaining lower utilisation is generally considered healthier than repeatedly maxing out credit cards.
A figure of around 30% or below is frequently mentioned as a practical credit-management guideline. However, borrowers should not interpret 30% as a universal or guaranteed CIBIL rule that automatically increases or decreases a score.
Instead, the broader objective should be to avoid consistently operating close to the maximum available limit.
If you hold multiple credit cards, monitor both your spending and available limits across your accounts. A higher credit limit should also not be treated as an invitation to increase unnecessary expenditure.
3. Don't Apply for Too Many Loans or Cards Within a Short Period
Submitting applications to several lenders within a short period can lead to multiple hard enquiries appearing on your credit report.
A hard enquiry generally occurs when a lender checks your credit profile while evaluating an application for a loan or credit card.
Applying for credit repeatedly over a short period may therefore affect how your credit-seeking behaviour appears in your credit profile.
Instead of sending applications to numerous lenders simultaneously, compare factors such as eligibility requirements, interest rates, processing fees, repayment terms and other conditions before formally applying.
Apply only for credit products that you genuinely need and for which you have a reasonable chance of meeting the lender's eligibility requirements.
It is also important to distinguish between checking your own credit information and a lender making a hard enquiry while processing a new credit application.
4. Don't Ignore Your Credit Report
Paying your bills on time is important, but monitoring your credit report is also useful.
Credit reports can occasionally contain information that needs correction or updating. For example, a closed loan may not have been updated correctly, an unfamiliar account may appear, or certain repayment information may require clarification.
Ignoring such issues for a long period can make them more difficult to address when you urgently need credit.
Consumers should periodically review their credit reports and check details such as active loans, credit cards, outstanding balances and repayment history.
If you notice an account that does not belong to you or information that appears inaccurate, raise a dispute through the appropriate credit bureau or lender process rather than simply ignoring the entry.
Can a Low CIBIL Score Be Improved?
A weak credit profile does not generally improve overnight. Credit scores are based on information reported over time, so building a stronger repayment record usually requires consistent financial behaviour.
Paying EMIs and credit card dues on time, keeping borrowing manageable, avoiding unnecessary credit applications and regularly checking your credit report can all support healthier credit management.
Borrowers should also avoid companies or individuals promising a guaranteed or instant increase in their CIBIL score in exchange for money. Legitimate negative information cannot simply be erased because someone charges a fee; genuinely incorrect information should instead be disputed through the appropriate process.
Good Credit Habits Matter Over the Long Term
A CIBIL Score ranges from 300 to 900, but lenders do not necessarily make approval decisions based on this number alone. Income, existing debt, repayment capacity, employment profile and the lender's internal eligibility criteria can also influence a credit decision.
For borrowers trying to protect or rebuild their credit profile, consistency is more useful than looking for shortcuts. Pay dues on time, avoid repeatedly maxing out credit cards, limit unnecessary loan applications and review your credit report periodically.
These habits may not produce an immediate jump in your score, but they can help establish a more responsible credit history over time and put you in a stronger position when you need to apply for a loan or credit card in the future.