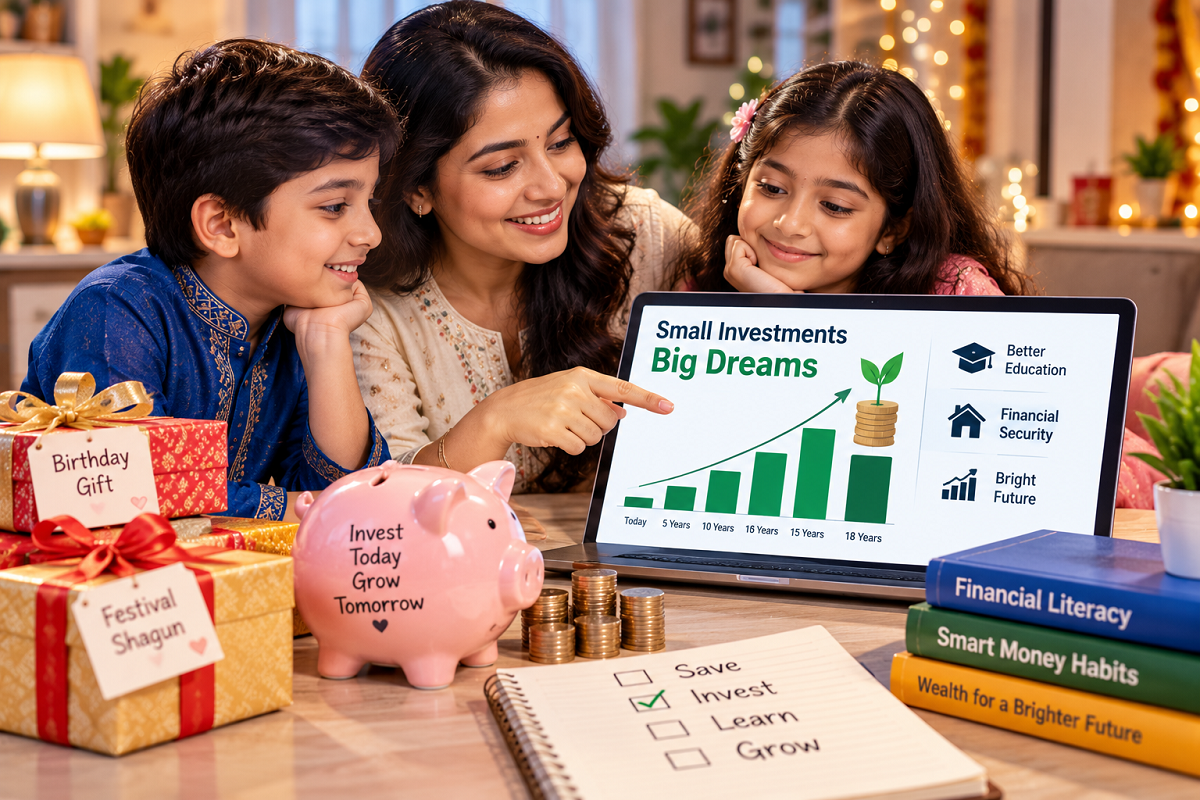
Birthdays and festivals such as Raksha Bandhan and Diwali often come with a familiar tradition in Indian families—children receiving cash as shagun from parents, grandparents and other relatives.
The envelope carries love and blessings, but the money inside may disappear surprisingly quickly. It might be spent on toys, snacks, games or other small purchases, and within a few weeks the child may barely remember where the money went.
There is another way parents can approach these occasional cash gifts. Instead of allowing every rupee to be spent immediately, a portion of the money could be directed towards a long-term investment in the child's name.
The objective does not have to be limited to creating a financial corpus. It can also become a practical way of teaching children how saving, investing, market fluctuations and compounding work.
Turn Shagun Into a Long-Term Financial Lesson
Parents generally plan separately for major expenses such as their children's education and other future needs. Those investments are usually managed entirely by adults, with children often having little idea that they exist.
A shagun-based investment can be different.
Parents can involve children in the process and explain what happens to the money they receive on birthdays or festivals.
For example, instead of simply telling a child that ₹500 has been invested, parents could periodically show them how the value of the investment has changed.
The goal is to gradually introduce the idea that money does not always need to be spent immediately.
Why Children Should Learn About Money Early
Families openly discuss school, health, friendships and careers with children, but conversations about personal finance are often postponed until adulthood.
As a result, young adults may begin earning money before they properly understand budgeting, investing, debt, risk or compounding.
Financial literacy does not necessarily require complicated lessons.
A child who occasionally looks at an investment statement with a parent can gradually learn basic concepts. Parents can explain why the investment increased during one period and declined during another.
Such conversations can also teach an important principle: market-linked investments do not rise continuously.
Can a Mutual Fund Investment Be Made for a Minor?
Mutual fund investments can be made in a minor child's name, subject to applicable rules and documentation.
Because the investor is a minor, a parent or legal guardian generally operates the investment until the child reaches adulthood. The required documentation and procedures can vary, so families should check the latest requirements with the relevant mutual fund house, registrar or authorized investment platform.
Once the child turns 18, additional formalities, including updated KYC and status-related requirements, may need to be completed before transactions can continue normally.
Parents should verify the current rules before opening or operating such an investment.
What Could ₹500 a Month Potentially Become?
Consider a simple illustration.
Suppose parents start investing ₹500 per month for a child from the age of five and continue until the child turns 18.
Over 13 years, the family would contribute around ₹78,000.
If the investment hypothetically generated an average annual return of around 12%, the accumulated amount could grow significantly beyond the original contributions over time.
However, the 12% figure should be treated only as an illustration—not a promised return. Mutual funds, particularly equity and index funds, are market-linked investments. Returns can fluctuate, and the final amount may be higher or lower than an illustration suggests.
This distinction is especially important when teaching children about investing.
Show Children Both Gains and Losses
Financial education should not focus only on periods when investments perform well.
Parents can consider sitting with their children every few months and reviewing the investment together.
When the value rises, explain why. When markets decline and the investment temporarily loses value, do not hide the fall.
Instead, use it as an opportunity to explain that financial markets fluctuate and that higher-return investments can also involve risk.
Children do not need to understand every technical term immediately. Concepts can be introduced gradually as they grow older.
Let Children Decide What Happens to Some Gift Money
Another useful approach is giving children some control over their shagun.
When the next birthday or festival arrives, parents can ask whether the child wants to spend the entire amount, save it or invest a portion.
Allowing children to make small financial decisions can help them understand the trade-off between immediate spending and delayed rewards.
A child who voluntarily chooses to invest ₹500 instead of spending it has begun to understand one of the foundations of personal finance: money can be used today, saved for later or invested for a longer-term objective.
Teenagers Can Learn Through Simulated Investing
Older children and teenagers can be introduced to more advanced concepts without immediately putting real money at risk.
Educational tools and simulated portfolios can help demonstrate how stock prices and portfolios move. A teenager can observe how a virtual portfolio responds when markets rise or fall while learning basic investment terminology.
Parents should ensure that any platform used by a child is age-appropriate, trustworthy and compliant with applicable rules.
Simulated investing should also be presented as education rather than a game of making quick money.
Understand the Tax Rules Too
Taxation is another area parents should not overlook.
Income arising from investments made in a minor's name can, in many circumstances, be subject to clubbing provisions under Indian income-tax rules, meaning it may be included in a parent's taxable income. Specific exemptions and exceptions may also apply.
Tax rules can change, and the treatment can depend on individual circumstances and the nature of the investment. Parents should therefore check the latest tax provisions or consult a qualified tax professional rather than relying solely on old examples.
The Bigger Gift Is Financial Awareness
The investment account itself may eventually accumulate a useful amount, but its greatest value could be the conversations it creates.
A child who grows up understanding the difference between saving and investing, the importance of patience, the impact of market risk and the power of long-term compounding may enter adulthood with financial knowledge that many people learn only after making costly mistakes.
So, the next time a child receives a birthday or festival envelope, parents do not necessarily have to take all the cash away from them.
Let them enjoy part of it if appropriate—but consider using another portion to introduce them to long-term investing.
The money may grow over time, but the financial habits and knowledge developed alongside it could prove to be the more valuable gift.
Disclaimer: This article is for general educational and financial awareness purposes only. Mutual fund investments are subject to market risks. Returns are not guaranteed, and investors should consider their financial situation, objectives and risk tolerance before investing.