LIFESTYLE
Loan Tips 2026: Avoid These 5 Costly Mistakes Before Taking a Personal, Home or Business Loan
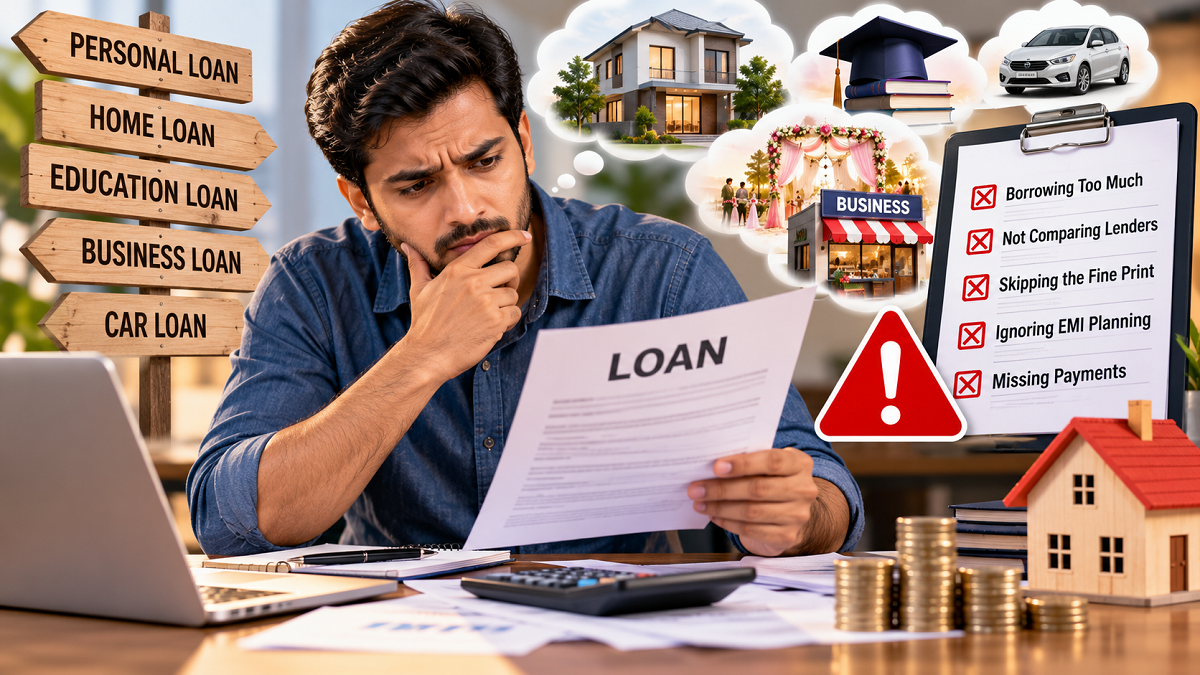
Loan Tips 2026: Taking a loan can help you achieve important financial goals, whether you are planning to purchase a house, fund your child's education, organize a wedding or expand a business. Banks and non-banking financial companies (NBFCs) offer several borrowing options to meet different financial requirements.
However, borrowing money without proper planning can create long-term financial difficulties. A loan that initially appears affordable may become expensive because of interest charges, processing fees, repayment conditions and other costs.
Many borrowers focus primarily on getting their loan application approved without carefully examining whether they can comfortably repay the amount.
Financial planning before borrowing is therefore essential. Understanding the loan terms, comparing lenders and calculating monthly installments can help you avoid unnecessary financial pressure.
Here are five important mistakes borrowers should avoid when applying for a loan.
1. Borrowing More Money Than You Actually Need
One of the most common borrowing mistakes is accepting a larger loan simply because the bank is willing to approve it.
Financial institutions generally evaluate loan eligibility based on factors such as monthly income, existing financial obligations, credit history and repayment capacity.
For example, a lender may approve a personal loan of ₹8 lakh even when the borrower requires only ₹4 lakh.
Taking the entire approved amount may seem attractive, but it also means paying interest on money that was not necessary.
A larger loan generally increases the monthly EMI, total interest burden or both.
Before submitting an application, calculate the exact amount required for your financial goal.
Consider using available savings where appropriate, while maintaining sufficient emergency funds.
Remember: Your maximum loan eligibility and your actual borrowing requirement are not necessarily the same.
2. Choosing a Lender Without Comparing Interest Rates
Another mistake is selecting the first bank or NBFC that offers a loan.
Different financial institutions may provide different interest rates, processing fees, repayment periods and additional charges.
Even a relatively small difference in interest rates can affect the total repayment amount, particularly for long-term loans.
Borrowers should compare offers from multiple regulated lenders before making a decision.
Pay attention to the Annual Percentage Rate (APR), where applicable, because it reflects the annualized cost of borrowing, including specified charges.
For loans covered by applicable RBI disclosure requirements, borrowers should also examine the Key Facts Statement (KFS), which provides important information about loan costs and conditions.
Do not compare offers based only on the advertised interest rate.
Processing charges, insurance costs where applicable, and other contractual expenses may significantly influence the overall borrowing cost.
3. Signing Loan Documents Without Reading the Conditions
Loan agreements contain important details about the borrower's financial responsibilities.
Unfortunately, some applicants sign these documents without reviewing the terms carefully.
This can create unexpected difficulties later.
Before accepting a loan, verify the applicable interest rate, repayment schedule, processing fees, late-payment charges and other contractual conditions.
Also determine whether the interest rate is fixed or floating.
A floating interest rate may change during the loan tenure, potentially affecting the EMI or repayment period.
Borrowers should also examine prepayment and foreclosure conditions.
Some loan categories may have restrictions on the charges lenders can impose, while other products may follow different contractual rules.
Understanding these conditions in advance can help avoid disputes and unexpected expenses.
If any clause is unclear, request an explanation from the lender before signing.
4. Ignoring Your Monthly EMI Repayment Capacity
A loan should fit comfortably within your household budget.
Before borrowing, calculate how much money remains after essential monthly expenses.
These expenses may include rent, groceries, school fees, utility bills, insurance premiums and existing loan installments.
You should also account for savings and emergency requirements.
For example, a borrower earning ₹50,000 per month may struggle with a new EMI of ₹20,000 if existing household expenses and other repayments already consume most of the income.
The affordability of an EMI depends on the individual's complete financial situation, not just salary.
Using an online EMI calculator can help estimate monthly payments under different interest rates and repayment periods.
A longer tenure may reduce the monthly installment but generally increases the total interest paid over the life of the loan.
Therefore, choose a repayment period that balances affordability with the overall borrowing cost.
5. Missing EMI Payments or Choosing the Wrong Due Date
Repayment discipline is important for maintaining financial stability and a healthy credit profile.
Missing an EMI can result in additional charges, depending on the lender's terms and applicable regulations.
Repeated or prolonged repayment delays may also negatively affect your credit history.
One practical way to reduce this risk is to choose an EMI due date that aligns with your salary or regular income cycle, where the lender offers that flexibility.
For example, if your salary normally arrives on the first day of every month, scheduling the installment a few days later may make repayment easier to manage.
Maintain sufficient funds in the linked bank account before the payment date.
Setting reminders or enabling authorized automatic payments can also help prevent accidental delays.
However, automatic payment arrangements should be monitored to ensure adequate account balances and successful deductions.
Why Your Credit Score Matters When Applying for a Loan
A borrower's credit history is another important consideration during loan approval.
Lenders may review credit reports to understand previous repayment behaviour and existing debt obligations.
A strong credit profile may improve access to certain borrowing options, although approval and pricing depend on the lender's policies and other eligibility criteria.
Late payments, excessive borrowing and repeated credit applications can affect how lenders assess an applicant.
Before applying for a significant loan, reviewing your credit report can help identify inaccurate information or outstanding obligations that require attention.
Borrowers should also avoid applying to numerous lenders unnecessarily within a short period.
Check the Total Loan Cost, Not Just the EMI
A lower EMI does not always mean a cheaper loan.
Consider an illustrative loan of ₹5 lakh at an annual interest rate of 12%, assuming a fixed rate and monthly reducing-balance calculation.
| Loan tenure | Approximate monthly EMI | Approximate total interest |
|---|---|---|
| 3 years | ₹16,607 | ₹97,858 |
| 5 years | ₹11,122 | ₹1,67,333 |
These calculations are illustrative and exclude processing fees, taxes and other applicable charges.
The example shows that extending the repayment period can make monthly installments more manageable while increasing the overall interest expense.
Borrowers should therefore compare both the monthly EMI and total repayment amount before selecting a tenure.
Important Checks Before Accepting a Loan Offer
Before finalizing any loan, confirm that the lender is appropriately regulated and that the loan terms are clearly disclosed.
Review the sanction letter, repayment schedule and relevant disclosures.
Make sure you understand whether additional products, such as insurance, are optional or mandatory under the particular offer.
Avoid paying unexplained advance charges to unknown agents or sharing sensitive banking credentials with unauthorized individuals.
If you are borrowing through a digital lending application, verify the identity of the actual regulated lender and carefully review the official loan documentation.
These precautions can help reduce the risk of financial fraud and misleading loan offers.
Final Takeaway
Loans can be useful financial tools when borrowed responsibly and repaid according to a realistic plan.
However, taking unnecessary debt, overlooking charges, ignoring agreement terms or missing installments can turn a manageable financial commitment into a serious burden.
Before taking any loan, compare lenders, borrow only what you need, calculate the total repayment cost and make sure the EMI fits your monthly budget.
A few careful decisions before signing the agreement can help protect your savings, credit profile and long-term financial stability.
Disclaimer: This article is for general financial awareness only. Loan eligibility, interest rates, fees and repayment conditions vary by lender and product. Review official loan documents and seek qualified financial advice when necessary.